Оригинал материала
Recharging the Dragon: China Energy Drinks Market Dynamics, Growth Projections, and Strategic Forecast (2026–2034)
The functional beverage landscape in China is undergoing a massive transformation. Driven by a fast-paced urban lifestyle, the rise of digital economies, and an unprecedented shift in consumer habits, energy drinks have evolved from niche athletic supplements into daily lifestyle essentials. According to comprehensive data from Renub Research, the market for energy drinks in China is positioned for sustained, high-velocity expansion. The market size is projected to climb from US$ 10.11 billion in 2025 to an impressive US$ 21.28 billion by 2034. This robust trajectory reflects a Compound Annual Growth Rate (CAGR) of 8,62% over the forecast period from 2026 to 2034.
This comprehensive market analysis explores the underlying growth engines, regional variations, packaging evolutions, distribution shifts, and competitive crosscurrents shaping the world’s most dynamic functional beverage arena.
Download Free Sample Report: https://www.renub.com/request-sample-page.php?gturl=china-energy-drinks-market-p.php
1. Market Outlook: The Rise of Functional Vitality in Urban China
An energy drink is fundamentally formulated to deliver rapid, short-term enhancements in mental alertness and physical performance. Typically fortified with active ingredients such as caffeine, taurine, sugar, B-complex vitamins, and traditional herbal extracts, these beverages serve as functional tools to combat physical exhaustion and cognitive fatigue.
In China, the demand for these products is no longer confined to professional athletes. The relentless pace of modern Chinese metropolitan life—often characterized by grueling corporate schedules, long commutes, and intense academic competition—has turned energy drinks into an indispensable daily resource. From white-collar professionals working the notorious "996" shift (9 AM to 9 PM, 6 days a week) to marathon e-sports gamers, university students, and long-haul logistics drivers, the consumer demographic has widened dramatically.
Domestic and international brands have successfully capitalized on this shift by leveraging aggressive digital marketing, high-profile sports sponsorships, and interactive social media campaigns tailored explicitly to Gen Z and millennial cohorts. While health advocates continue to highlight the risks of excessive consumption—such as sleep disruption or caffeine sensitivity—the market remains remarkably resilient. This durability is supported by competitive pricing structures, omnipresent retail availability, and immediately recognizable functional efficacy.
2. Core Macroeconomic and Cultural Growth Drivers
Rapid Urbanization and the High-Pressure Corporate Ecosystem
The rapid relocation of China’s population from rural regions to tier-1, tier-2, and tier-3 cities remains a foundational engine of beverage market volume. With urban centers holding a commanding share of the national population, the structural lifestyle of the average consumer has shifted toward high-efficiency, high-stress routines. The cultural phenomenon of Neijuan (involution or hyper-competition) across corporate offices, factories, and tech hubs creates widespread fatigue. Energy drinks provide an accessible, low-cost mechanism to sustain productivity throughout extended shifts, making them functional staples within industrial zones and commercial financial districts alike.
The Esports Boom and Youth Gaming Culture
The intersection of youth culture, digital entertainment, and functional food chemistry has opened up a highly profitable market segment. Demographics aged between 15 and 35 represent the core consumption tier for energy products. China’s status as a global epicenter for esports and live streaming has institutionalized the relationship between prolonged gaming sessions and functional energy support. Brands have recognized this synergy, establishing deep investment channels into professional esports tournaments, gaming house sponsorships, and co-branded interactive product rollouts
E-Commerce Integration and Formulation Innovation
The rapid growth of China’s retail framework has fundamentally altered how consumers discover and buy beverages. The traditional brick-and-mortar footprint is now fully integrated with O2O (Online-to-Offline) delivery networks, instant-commerce platforms, and live-stream shopping storefronts. This hyper-accessible retail network operates alongside aggressive product R& D. To capture increasingly health-conscious consumers, manufacturers are actively diversifying beyond legacy high-sugar formulations. The market is seeing a surge in low-calorie options, sugar-free variants, and drinks infused with traditional Chinese medicine (TCM) botanicals like ginseng, wolfberry, and red dates.
3. Structural Barriers and Industry Challenges
Increasing Regulatory Oversight and Health Awareness
The primary headwind facing manufacturers in mainland China is the dual pressure of consumer wellness trends and tightening government supervision. As public awareness around metabolic health, diabetes prevention, and cardiovascular wellness deepens, high-sugar, high-caffeine beverages face closer scrutiny. The State Administration for Market Regulation (SAMR) has consistently raised the bar for functional food labeling, advertising transparency, and maximum permissible synthetic caffeine limits. Furthermore, potential constraints on marketing directly to minors require brands to carefully re-engineer their promotional playbooks while formatting clear, health-oriented value propositions.
Market Saturation and Aggressive Price Competition
The Chinese functional beverage ecosystem is highly crowded. Brands face intense competition from global giants with massive marketing budgets, alongside agile, cost-efficient domestic players offering highly competitive retail pricing. This environment often triggers localized price adjustments, squeezing profit margins and raising the cost of customer acquisition. Because many standard formulations offer similar functional benefits—such as increased focus or fatigue reduction—brand loyalty can be fluid. Consumers frequently switch brands based on immediate store availability, discount bundles, or trending viral marketing. This volatility is intensified by overlapping functional categories, such as sports hydration drinks, RTD (Ready-to-Drink) coffees, and fortified teas, which compete directly for the same shelf space.
4. Segment Analysis: Packaging Formats and Product Categories
The Dominance of PET Bottles
Polyethylene terephthalate (PET) plastic bottles remain a dominant packaging format across China’s energy drinks landscape. The reasons are inherently practical: PET bottles are lightweight, shatterproof, and critically, re-closable. This makes them highly compatible with the lifestyle of construction workers, transport operators, and students who consume their beverages gradually throughout a shift or school day. From a manufacturing perspective, PET molding is highly cost-effective, allowing brands to offer higher liquid volumes at competitive retail price points. This appeals directly to value-conscious demographics outside major tier-1 cities.
Premium Positioning of Aluminum Cans
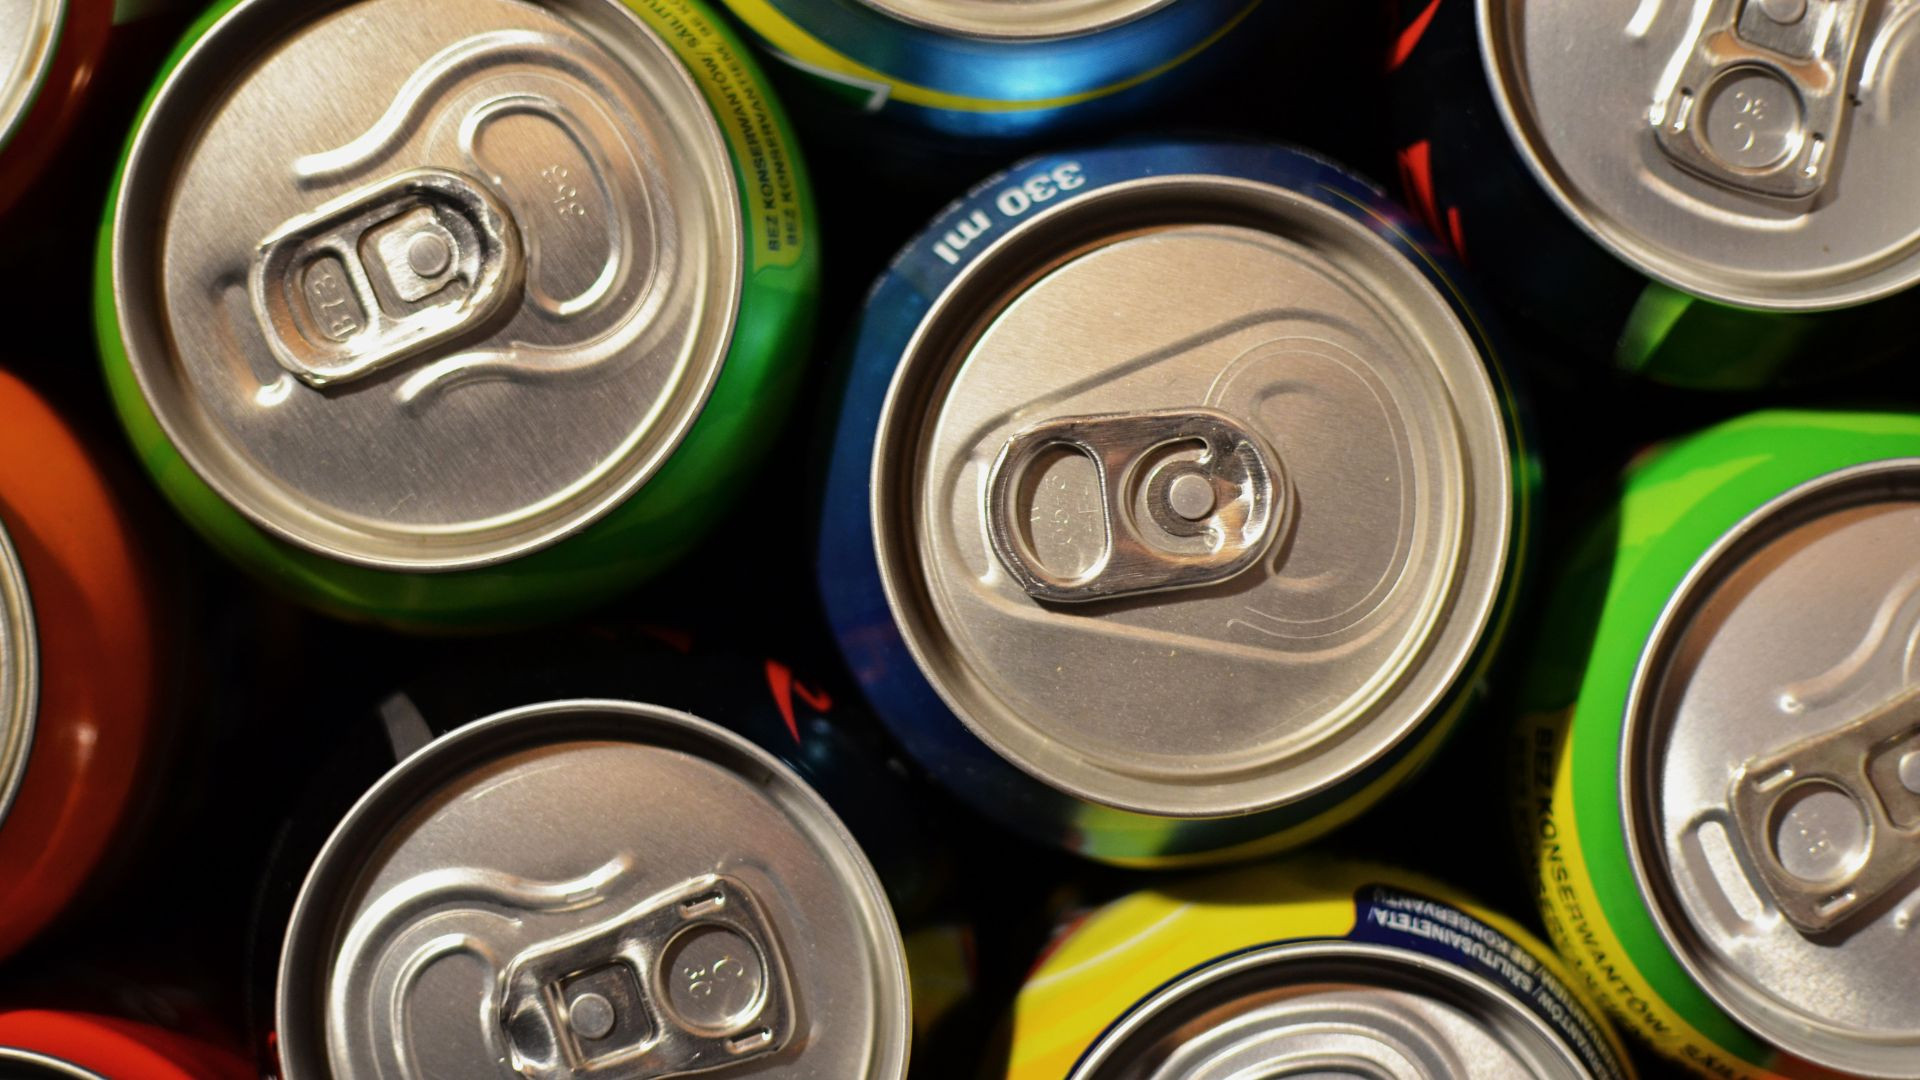
Canned energy beverages represent the premium, lifestyle-focused segment of the market. Typically associated with international brands and high-end domestic lines, aluminum cans are heavily utilized in experiential marketing campaigns across music festivals, gyms, and esports arenas. The physical properties of metal cans allow for fast cooling, making them popular for immediate consumption out of convenience store refrigeration units. The rigid exterior also serves as a canvas for sleek matte designs, tactile finishes, and limited-edition pop-culture collaborations that resonate with design-conscious urban consumers.
The Emerging Energy Shots Niche
Energy shots represent a highly concentrated, fast-acting sub-category within the broader functional mix. Packaged in miniature vials, these products dispense with high liquid volume in favor of an immediate, potent dose of active ingredients. This segment caters perfectly to time-poor corporate executives, travelers, and students who require immediate alertness without the fluid volume of a traditional 500ml container. While premium pricing models and historically lower consumer familiarity have limited mass adoption, ongoing innovations—such as sugar-free concentrations and vitamin-packed clean formulations—are steadily carving out a loyal urban consumer base.
5. Regional Market Breakdown
Beijing
As the political and academic capital, Beijing exhibits a highly sophisticated demand matrix. The city’s dense concentration of tier-1 universities, research institutions, and corporate headquarters creates a reliable, structurally stable consumer base. Given the highly educated local demographic, premium formulations that emphasize clean ingredients, natural caffeine sources, and verifiable health benefits perform exceptionally well. Regulatory compliance here is vital, with consumers paying close attention to clear ingredient disclosures and nutritional profiles.
Shanghai
Shanghai serves as the primary gateway for premium lifestyle trends and international product concepts in China. Driven by a global financial ecosystem, a busy white-collar community, and a diverse nightlife culture, the city is a prime market for high-end energy brands. Shanghai’s consumers show a strong preference for functional innovations, including zero-sugar varieties, complex amino-acid blends, and sleek packaging styles. The city’s extensive network of premium convenience chains and boutique retail outlets ensures continuous, high-visibility placement for new product rollouts.
Jiangsu
An economic powerhouse characterized by expansive industrial zones, high-tech manufacturing parks, and growing urban centers like Nanjing and Suzhou, Jiangsu offers a balanced market landscape. The presence of a massive industrial and logistics workforce creates steady demand for mass-market, high-volume energy products, particularly in cost-efficient PET bottles. Concurrently, rising disposable incomes in its urban centers are driving increased adoption of premium canned alternatives, making the province a vital volume and revenue driver.
Fujian
Fujian’s market dynamics are shaped by its coastal trade networks, busy port cities like Xiamen and Fuzhou, and a strong entrepreneurial business culture. The logistics, maritime transport, and private manufacturing sectors drive consistent demand for functional beverages tailored to long, physically demanding work shifts. While the region retains a deep-rooted traditional tea culture, energy drinks have successfully established themselves as complementary functional utilities, expanding through convenience stores and local wholesale distribution networks.
6. Retail Distribution Channel Deep Dive
The operational health of China’s energy drink market relies heavily on a diverse, multi-channel distribution network. Each channel plays a specific role in capturing consumer demand:
- Convenience Stores (C-Stores): Chains such as 7-Eleven, FamilyMart, Lawson, and local variants like Easy Joy operate at the frontline of impulse purchasing. Positioned inside transit hubs, commercial high-rises, and nightlife districts, their 24/7 operating hours make them the go-to destination for immediate energy needs. High-visibility shelf placement near checkout counters and chilled beverage vaults significantly drives daily sales volume.
- Hypermarkets and Supermarkets: These formats remain essential for volume-driven bulk purchases, family provisioning, and multi-pack promotions. They offer extensive shelf space, allowing brands to showcase their full product portfolios, from legacy formulas to experimental line extensions.
- Online E-Commerce Platforms: Horizon-wide digital marketplaces like Tmall, JD.com, and social commerce engines like Douyin have transformed brand discovery and bulk distribution. E-commerce allows brands to deploy targeted data marketing, launch online-exclusive flavors, and bypass geographic retail limitations to reach tier-4 cities and beyond.
7. Competitive Landscape and Strategic Key Players
The marketplace features a mix of well-established multinational brands and aggressive, highly localized domestic corporations. Key players driving innovation and infrastructure investment include:
- Red Bull: The pioneering force in the functional beverage category, maintaining a powerful brand equity and market share through its recognizable gold cans and extensive event marketing footprint.
- Monster Beverage Corporation: Capitalizing heavily on lifestyle positioning, Monster dominates the esports, extreme sports, and youth alternative sub-cultures with its diverse flavor profiles and distinctive branding.
- Taisho Pharmaceutical: Leveraging a clinical, health-first heritage, its formulations focus on providing functional energy supported by pharmaceutical-grade quality standards.
- Dali Food Group Co., Ltd.: A domestic consumer goods powerhouse, Dali utilizes its massive nationwide distribution infrastructure and value-driven pricing models to capture large market share across rural and semi-urban geographies.
- Coca-Cola Company & PepsiCo: Both global beverage giants utilize their massive distribution networks, deep retail relationships, and cross-branding capabilities to scale functional portfolios and capture emerging zero-sugar sub-segments.
- Eastroc Beverage (Southland Trade Company Ltd.): A key domestic success story, Eastroc has captured significant market share through functional packaging design (including its signature dust-cap PET bottle) and highly competitive pricing tailored to working-class urban consumers.
- Hangzhou Wahaha Group Co., Ltd.: A long-standing giant in the domestic beverage sector, Wahaha uses its localized production capabilities and deep retail penetration across tier-3 and tier-4 regions to keep functional energy accessible to a broad consumer base.
8. Data-Driven Market Overview
Based on the market modeling provided by Renub Research, the following structural trajectory highlights the expanding economic value of the China Energy Drinks sector:
Metric / ParameterHistorical Base Year (2025)Forecast Horizon Year (2034)Compounded Growth Metric (2026–2034)Total Market ValuationUS$ 10.11 BillionUS$ 21.28 BillionProjected CAGR: 8,62%Primary Growth DriversUrbanization TrendsYouth & Esports ExpansionRetail Channel Innovation & Clean-Label R& DCore Packaging TiersPET Bottles (Volume King)Aluminum Cans (Premium Tier)Concentrated Energy Shots (Niche Growth)
9. Comprehensive FAQs (Powered by Renub Research Data)
Q1: What is the projected market size of the Chinese energy drinks industry by 2034 according to Renub Research?
A: According to the forecast models generated by Renub Research, the total market size for energy drinks in China is projected to reach US$ 21.28 billion by the year 2034.
Q2: What is the baseline market valuation recorded at the start of the forecast track in 2025?
A: The market valuation for the Chinese energy drinks sector is estimated to sit at US$ 10.11 billion in 2025, serving as the baseline for the nine-year forecast horizon.
Q3: What is the calculated growth rate (CAGR) of the market over the 2026–2034 expansion period?
A: The China energy drinks market is projected to expand at a steady Compound Annual Growth Rate (CAGR) of 8,62% from 2026 to 2034.
Q4: According to research observations, which macro-demographic factors are driving this multi-billion dollar growth?
A: The expansion is primarily driven by three macroeconomic trends: rapid urbanization rates, rising consumer demand for functional health beverages amidst high-pressure work environments, and a large, digitally active youth population.
Q5: How does urbanization specifically impact consumer demand metrics within Renub Research’s market analysis?
A: Urbanization accelerates lifestyle speeds, increases average working hours (such as the corporate corporate office environment), and extends commutes. This creates structural fatigue across white-collar workers, students, and factory operators, turning energy drinks into a functional daily tool to sustain alertness.
Q6: What role do young consumers and the esports sector play in driving market demand?
A: Consumers aged 15 to 35 represent the core purchasing engine. The rapid expansion of China’s professional gaming and esports landscape has made energy drinks a lifestyle staple for improving focus during long digital streaming and competitive gaming sessions.
Q7: What product innovations does the market analysis identify as essential for brands to remain competitive over the forecast period?
A: To sustain market share amidst shifting health trends, brands must actively innovate by introducing low-calorie formulations, completely sugar-free variations, customized local flavor profiles, and products infused with traditional herbal or vitamin-added ingredients.