
Translated material
Sizifov ruble
The national currency can go uphill for a long time, but the fall promises to be swift
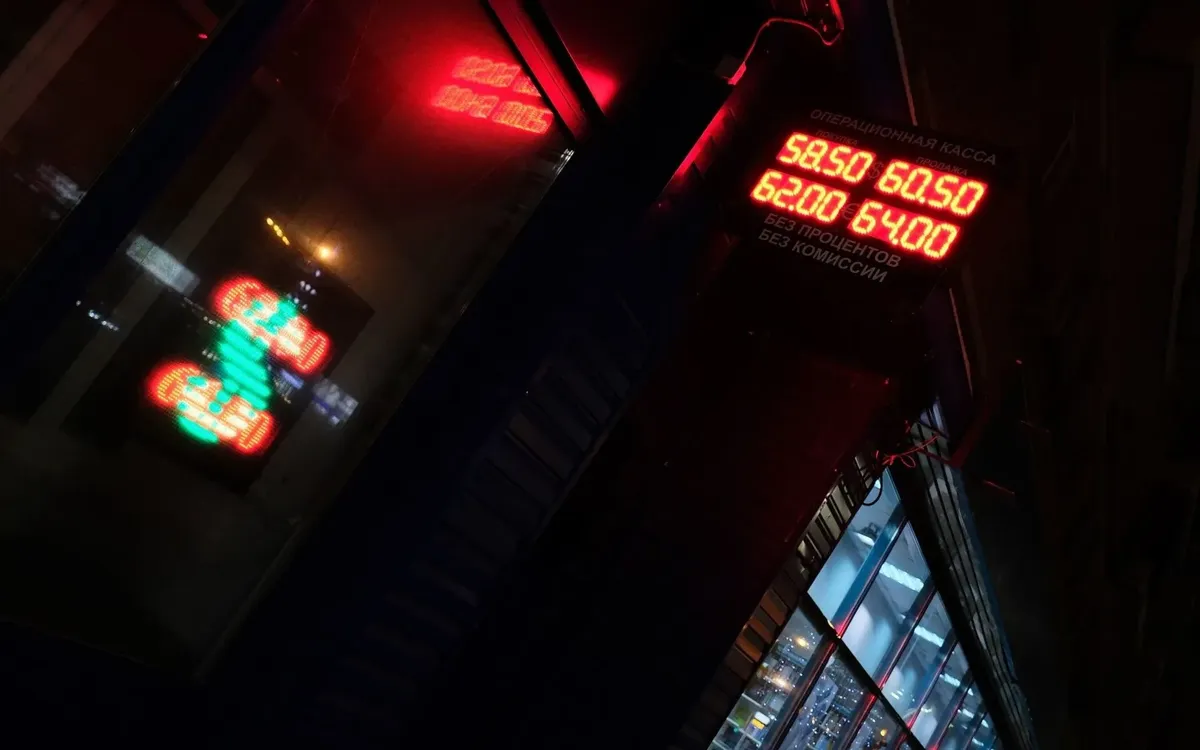
Last week, the dollar exchange rate for the first time in 1.5 years broke a level of 57 rubles. The positive dynamics of the Russian currency is associated with a reduction in the level of oil production in the OPEC countries, which, according to the energy agency, is performed by about 90%. In relation to the beginning of January, the ruble has already grown by 5–7% - the unexpected strengthening of the currency carries serious risks for the budget and forces the authorities to convince the market in a imminent reversal.
The main growth driver is the influx of foreign capital due to the much higher profitability of Russian assets compared to countries with a similar risk level, said the finama analyst Timur Nigmatullin. “Investors buy ruble bonds and earn at the expense of high interest rates in the country ( this phenomenon is called Carry Trade. - A. Kh. ). The course risks are minimal due to the reduction in oil production in OPEC countries, so this is a win -win investment strategy, ”the expert says.
The head of the Ministry of Economic Development Maxim Oreshkin said that the tendency to strengthen the Russian currency is seasonal and does not need interference on the part of the government. The key of seasonal factors is the reduction in imports of imports, explains the analyst of Metalinvestbank Sergey Romanchuk: in January, the purchases of consumer goods are greatly reduced after the December holidays. The schedule of payments on external debt also affects - this year there were no major payments.
Additional support for the ruble could provide an influx of currency on the Russian market due to a privatization transaction for the sale of a package of Rosneft shares, but the complete opacity of the operation does not allow us to draw accurate conclusions.
Carry Trade and a decline in payments against external debt repayment are important current factors, but the long -term dynamics of the ruble exchange rate determines the Russian trade balance. The ratio of export/imports primarily depends on the cost of oil. “The ruble exchange rate is fundamentally justified by oil prices, another question is that recently they are more or less standing still. But we see that the market is still actively reacting to the news from OPEC, ”says Romanchuk.
A little more than a year ago, oil prices were at $ 27 per barrel, now - $ 55 per barrel. The quotes increased more than half, while the ruble strengthened noticeably weaker. “Changing oil prices has a rapid effect on the ruble due to speculative operations, but serious cash flows - payment under large contracts - are behind the time from fluctuations in prices for six months or more,” says Sergey Khestanov, adviser to the opening broker. To some extent, the prolonged growth of the ruble is an extended reaction to the rise in price of oil about six months ago, the economist believes.
According to official figures, the budget depends on exports by about 43%, but this figure is not quite reliable: it does not take into account a business that does not engage in hydrocarbons, but serves the activities of exporters, says Hestanov. Real dependence is significantly higher - in the region of 60-65%. “The structure of the federal budget makes a very simple decision logic. She makes a high probability of weakening the ruble in the future, ”says the expert.
A correction has already occurred on the market - on February 18, the official dollar exchange rate amounted to 57.6 rubles, although it previously dropped to 56.7 rubles.
“It may well be that we have passed the lower point ...
An analysis of the payment balance shows that at current oil prices in the middle of the year we must reach the rate of 61-63 rubles per dollar, ”says Romanchuk. Nigmatullin believes that between the first and second quarter the dollar may reach 65 rubles, and by the end of the year to strengthen again.
In addition to oil prices against the ruble, a new set of seasonal factors will play, such as a more intense schedule for external debt. The operations of the Central Bank for the purchase of currency to replenish reserves are distributed over time, but the cumulative effect of them should weaken the ruble by 5-10% per year. Other important variables are a possible increase in the Fed’s rate and the policy of the American administration, which, in all likelihood, is not yet going to weaken the sanctions regime against Russia.
The strengthening of the ruble was monotonous and quite long, but the reverse movement can be swift. “Scenarios are possible when the growth of the dollar will be very fast - this is a spring that is compressed and then shoots,” Romanchuk notes.